Key Takeaways:
- Learn about the rising mortgage arrears in Ontario.
- Discover what causes homeowners to struggle with payments.
- Find out how to handle payment difficulties early.
- Understand the risks of private mortgages.
- Get tips on managing finances and investments effectively.
Introduction
Well, things are getting interesting in Ontario’s mortgage world. Recent findings show mortgage arrears are climbing, and it’s making both homeowners and investors sit up and pay attention. Mortgage arrears—simply put, that means you’re late on your mortgage by 90 days or more—are showing a disturbing rise. Especially in the nice spots like Greater Toronto and Hamilton Area (GTHA) and Southwestern Ontario. Can you feel the financial vibes shifting?
Our pals over at Canada Mortgage and Housing Corporation (CMHC) are waving red flags these days, pointing out the rising trend of mortgage arrears. You might ask, “Why does it matter?” Well, when folks can’t pay up, it ripples out, affecting the entire economic pond and housing market. This is a must-know territory for anyone with financial ties in Ontario.
For homeowners, the thought of falling behind on mortgage payments is spine-chilling. For the investors with a nose for sniffing out opportunities, it’s all about risk management now. With projections telling us that arrears will keep ticking upwards until the middle of 2027, staying informed is not just a hobby—it’s kind of essential. Keep one eye on the trends, keep chatting with your lender, and maybe reevaluate some of those financial plans to keep up with Ontario’s evolving mortgage scene.
What are Mortgage Arrears?
So, what’s the story with mortgage arrears? Simply, you’re in the arrears club if you’ve missed your mortgage payment by 90 days or more. It’s a serious chat, because once you’re in arrears, it’s ringing alarm bells for your finances. Missing a payment on occasion, sure—life happens—but in arrears? That’s a big ‘whoops’ to deal with.
When more people join the arrears club, the effects spread. Homeowners face potential extra fees and their credit score takes a dive; lenders get headaches as they may need to deal with foreclosure situations, which no one finds fun. Oh, and the neighborhood feels it too, when too many homes are in distress, property values can start a downward dance.
As Ontario gears up for more of these cases, everyone needs to keep a close watch. Homeowners need some financial mindfulness to act fast if payments become painful. Understanding these arrears and their ripple effects gets everyone on better footing to handle what comes. Think of it like radar for your wallet—it’s best to see what’s coming before it arrives.
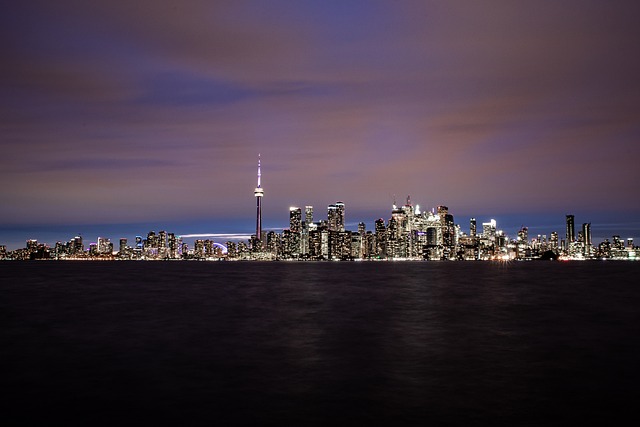
Current Trends in Ontario Mortgage Arrears
It’s not just chatter on the street; Ontario’s seeing a real uptick in mortgage arrears. It’s getting tough out there, with more people barely keeping up with payments. This arrears rate kinda ticks like a clock indicating stress levels among borrowers. Historically, Ontario’s been pretty chill in terms of arrears compared to other spots, but economic clouds are forming.
CMHC is laying out forecasts that paint a picture of rising arrears till mid-2027. We’re talking about economic uncertainty and market condition changes adding some spice to the mix. As arrears go up, the whole shebang, including homeowners, lenders, and communities, feel the pressure—which could lead to more bank owned homes or sales under financial duress.
Sure, this feels different from the financial crises we’ve known. Back then, interest rates were mental, economic slowdown felt like a full-stop. Now? We’re dealing with those old stressors plus the pandemic’s aftermath. Keep your eyes peeled, homeowners and investors, on this terrain. Stay aware, plan smart, and you might just dodge the bumpier rides ahead in your financial journey.
Regional Vulnerabilities: GTHA and Southwestern Ontario
The Greater Toronto and Hamilton Area (GTHA), along with Southwestern Ontario, are kind of the hot spots for mortgage arrears drama right now. Why there, you ask? Well, consider job market changes; a lot of folks are on shaky ground job-wise, making it tougher to meet mortgage commitments.
Home prices rising in these regions certainly don’t help. Buying pricier homes often means bigger mortgages, and any uptick in interest rates can put homeowners in a squeeze situation. Let’s not forget about high household debt levels—no one likes heading into a financial storm without any protection.
When borrowing costs climb, it just adds another layer of trouble. The labor-market uncertainty, volatile housing prices, sizable debt—it all mixes into a cocktail that makes staying abreast on mortgages a real challenge here. Homeowners, investors, get your financial defense game strong, ’cause it might just save your neck.
Early Warning Signs of Financial Stress
Financial stress has its way of sneaking up, but catching those hints early makes a world of difference in keeping mortgage arrears at bay. A telltale sign is the increasing reliance on credit to cover basics like utility bills or groceries—if you’re scraping the savings pot more often or your credit card bill is a mountain, consider it a sign.
A change in your financial situation coming up soon? Like being laid off or having your hours slashed? That can wreak havoc on your budget, putting mortgage payments in jeopardy. Be mindful of any adjustment in interest rates too; that adjustable rate can turn unfriendly super quickly.
Check out your finances regularly—a budget can tell you everything you need about your spending vs. income balance. Having a little emergency stash for life’s surprises helps too. Look at it like building a financial safety net to catch you before you tumble into mortgage arrears.
The Role of Private Lenders and Mortgage Investment Companies
Private lenders and mortgage investment companies are turning heads in Ontario’s mortgage scene. They’re a different breed from the traditional banks: less strict, more flexible. Sounds good? Maybe, but hold on—these terms usually lead to higher interest rates and, consequently, higher arrears rates.
Investors eyeing this sector find the allure of high returns intoxicating but let’s not ignore the arrears risk factor. It’s crucial to properly vet potential borrowers, ensuring they’re up for the challenge of meeting payment obligations. Investors need to hold the fort with solid risk management tactics.
With mortgage arrears on the upward path through 2027, private lenders need to stay on their toes. That means staying involved and informed about borrowers’ financial situation, so defaults aren’t a nasty surprise. The private mortgage market in Ontario is filled with both opportunities and hurdles; borrow carefully and invest wisely.
Strategies for Homeowners Facing Payment Difficulties
If you’re struggling with mortgage payments, know that there is a way forward. Communication upfront with your lender can make all the difference—they’ve got options to adjust payment terms or maybe offer some wiggle room. Give your budget a deep dive too, see where you can trim the fat to keep those payments on track.
Could you pick up a side hustle or rent a spare room? Those can be temporary relief avenues. If downsizing or selling is on the table, ponder it carefully; it’s a big step that can lighten the financial load substantially but comes with its set of consequences.
Financial counselors or advisors are friends in times like these—they can help navigate through the mess. The earlier you face payment troubles, the better positioned you’ll be to avoid foreclosure and stick to a financial game plan. Staying proactive? It’s like financial armor blocking potential hits.
What Mortgage Investors Should Watch
If you’re into mortgage investments in Ontario, keep your ear to the ground as arrears are peaking through ‘27. With more owners having a tougher time making payments, your investments could feel the strain. The key? Focusing on a few areas that really count.
First, vigorous underwriting practices are a must. Dig into potential borrowers’ histories to ensure they’re likely to pay back. Scan their credit, income situation, you know, the works. It’s about learning if they can actually walk the walk.
Keep tabs on your mortgage portfolio regularly—a proactive approach can help detect any issue before it’s shouting distance. Live in limbo? Nah, knowing your borrower’s locale, whether like GTHA or not, adds foresight to the mix, helping face varied economic pressures.
Diversification can be your friend here. Spread those investments, make ‘em wide and varied, and cushion yourself from potential turbulence. Don’t leave all eggs in one basket—wise handling keeps your portfolio ready to face the shifting landscape head-on.
Is Canada Facing a Mortgage Crisis?
As we’re analyzing these climbing arrears in Ontario, it begs the question: Are we hitting a nationwide mortgage meltdown point? Dive into this with CMHC insights, and you’ll get an educated take—things aren’t quite at crisis levels but there are spots to watch.
Here’s the scoop. Mortgage stress isn’t a uniform blanket across Canada. High-pressure zones like Ontario’s GTHA are dealing with more mounting arrears; other regions, with reasonable housing prices or solid economies, are facing different flavors of stress.
Look into local economic flavors; job stability, income levels, and borrowing costs cook into a stew affecting mortgage payment handling. Unwelcomed factors in these areas rake up more arrears, whisking up financial distress.
The big mortgage picture relies on how everyone—from policymakers to the homeowners themselves—manages these hurdles. Streamline efforts to smoothen regional gaps and lending practices, and Canada might steer clear of a mortgage storm. Stay informed, proactive, and ready to dodge roadblocks and you stand strong in this ever-twisting financial landscape.
Conclusion
After unpacking Ontario’s mortgage trends and investing into the big picture of arrears, folks, it’s time to gear up. Mortgage arrears are climbing till mid-2027, thanks to financial blips and debt levels defining the times for both homeowners and investors. Knowing these elements is key, whether you hold a mortgage directly or dive into mortgage-backed securities.
Homeowners, keep an eye on those financial hiccups—spotting signs early like struggling with bills or swiping the credit card too much; that’s your cue to act. Chatting with lenders and checking all the cards on the table might just keep stormy skies at bay. Investors? Keep tabs, craft smart strategies, keeping those portfolios storm-proof.
The private mortgage field? It’s a jungle with promises and pitfalls. Responsible borrowing and cautious investment go hand in hand in avoiding financial trouble spots.
Going forward, this knowledge packed trip should drive home reality checks and plan action. Keep nimble, stay in the know to ride the ups and down of Ontario’s mortgage scene. Ask yourself: how’s your financial armor holding up? Adjusting those straps now could mean you stand firm and ready for what’s swirling ahead. Stay strong out there!
If you enjoyed this article, and is someone interested in learning more about investing, particularly about our mortgage fund, be sure to join our VIP list here.